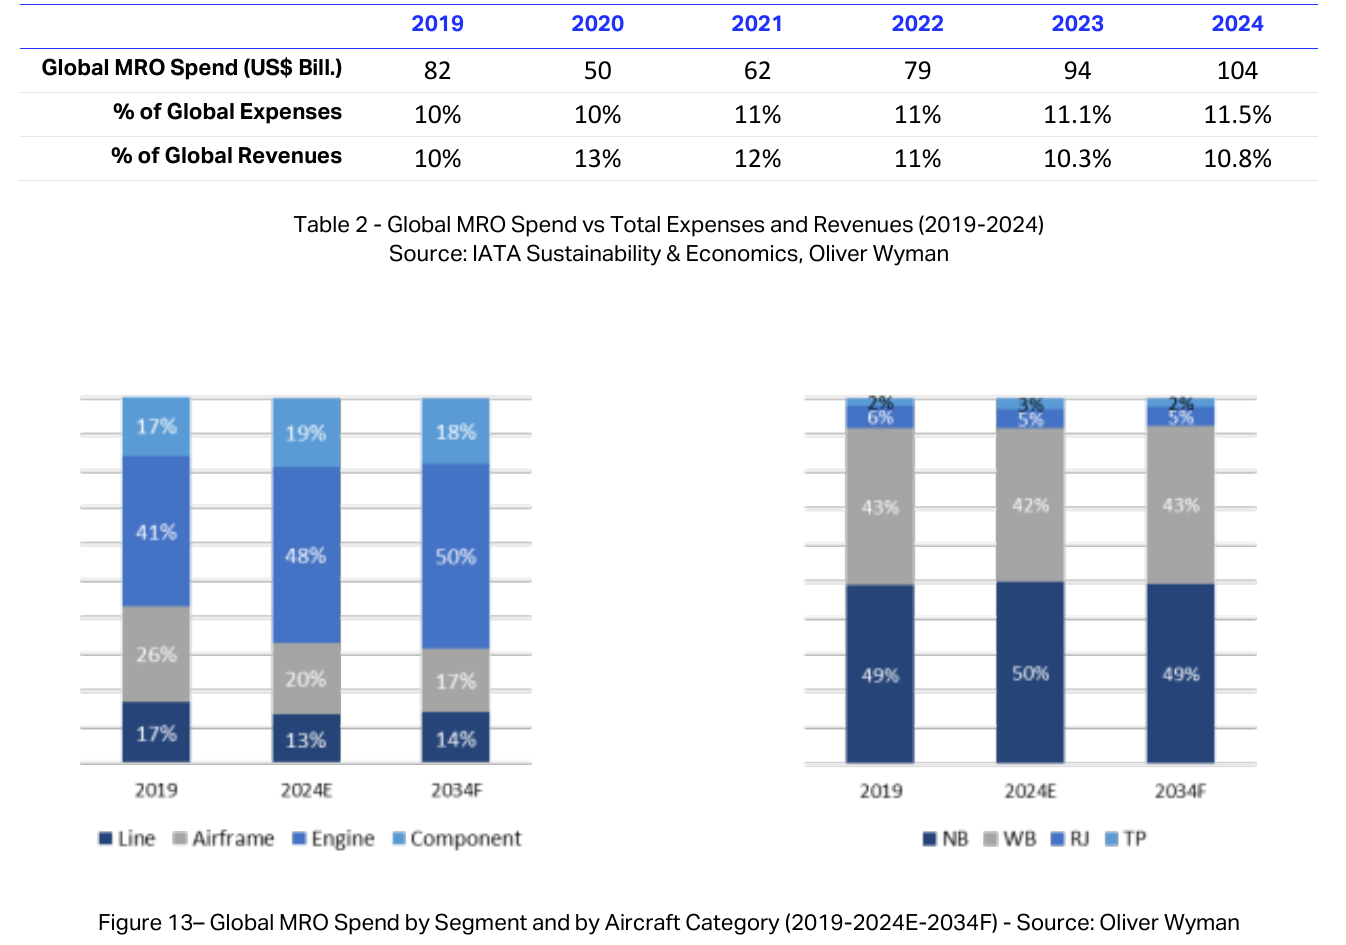
Engines now account for the largest share of global aircraft maintenance spending, based on a chart in IATA's FY2024 Maintenance Cost data eXchange executive report that draws on Oliver Wyman data. Engine work made up 41% of global MRO spend in 2019, 48% in the 2024 estimate, and 50% in the 2034 forecast.
Component maintenance followed a similar path, going from 17% in 2019 to 19% in the 2024 estimate and 18% in the 2034 forecast. Airframe maintenance moved the other way, falling from 26% in 2019 to 20% in 2024 and a projected 17% in 2034. Line maintenance went from 17% to 13% and is forecast at 14% in 2034.
The report links the shift to utilization. Higher flight hours, cycles and daily activity raise demand for engine and component work, while airframe maintenance depends more on calendar intervals, aircraft age and fleet management practices.
Spending by aircraft category has stayed steadier. Narrowbody aircraft accounted for 49% of MRO spend in 2019, 50% in the 2024 estimate and 49% in the 2034 forecast. Widebodies held 43%, 42% and 43% across the same years, while regional jets were 6%, 5% and 5%, and turboprops were 2%, 3% and 2%. The report notes that widebodies represent only 20.3% of the active fleet but account for 42% of total MRO costs.
Total spend was $104 billion in 2024, equal to 11.5% of global airline expenses.
Source: IATA -- https://www.iata.org/contentassets/8437020db31a4717b70677d9b06b1a45/fy2024-mcx-report_public.pdf#page=20