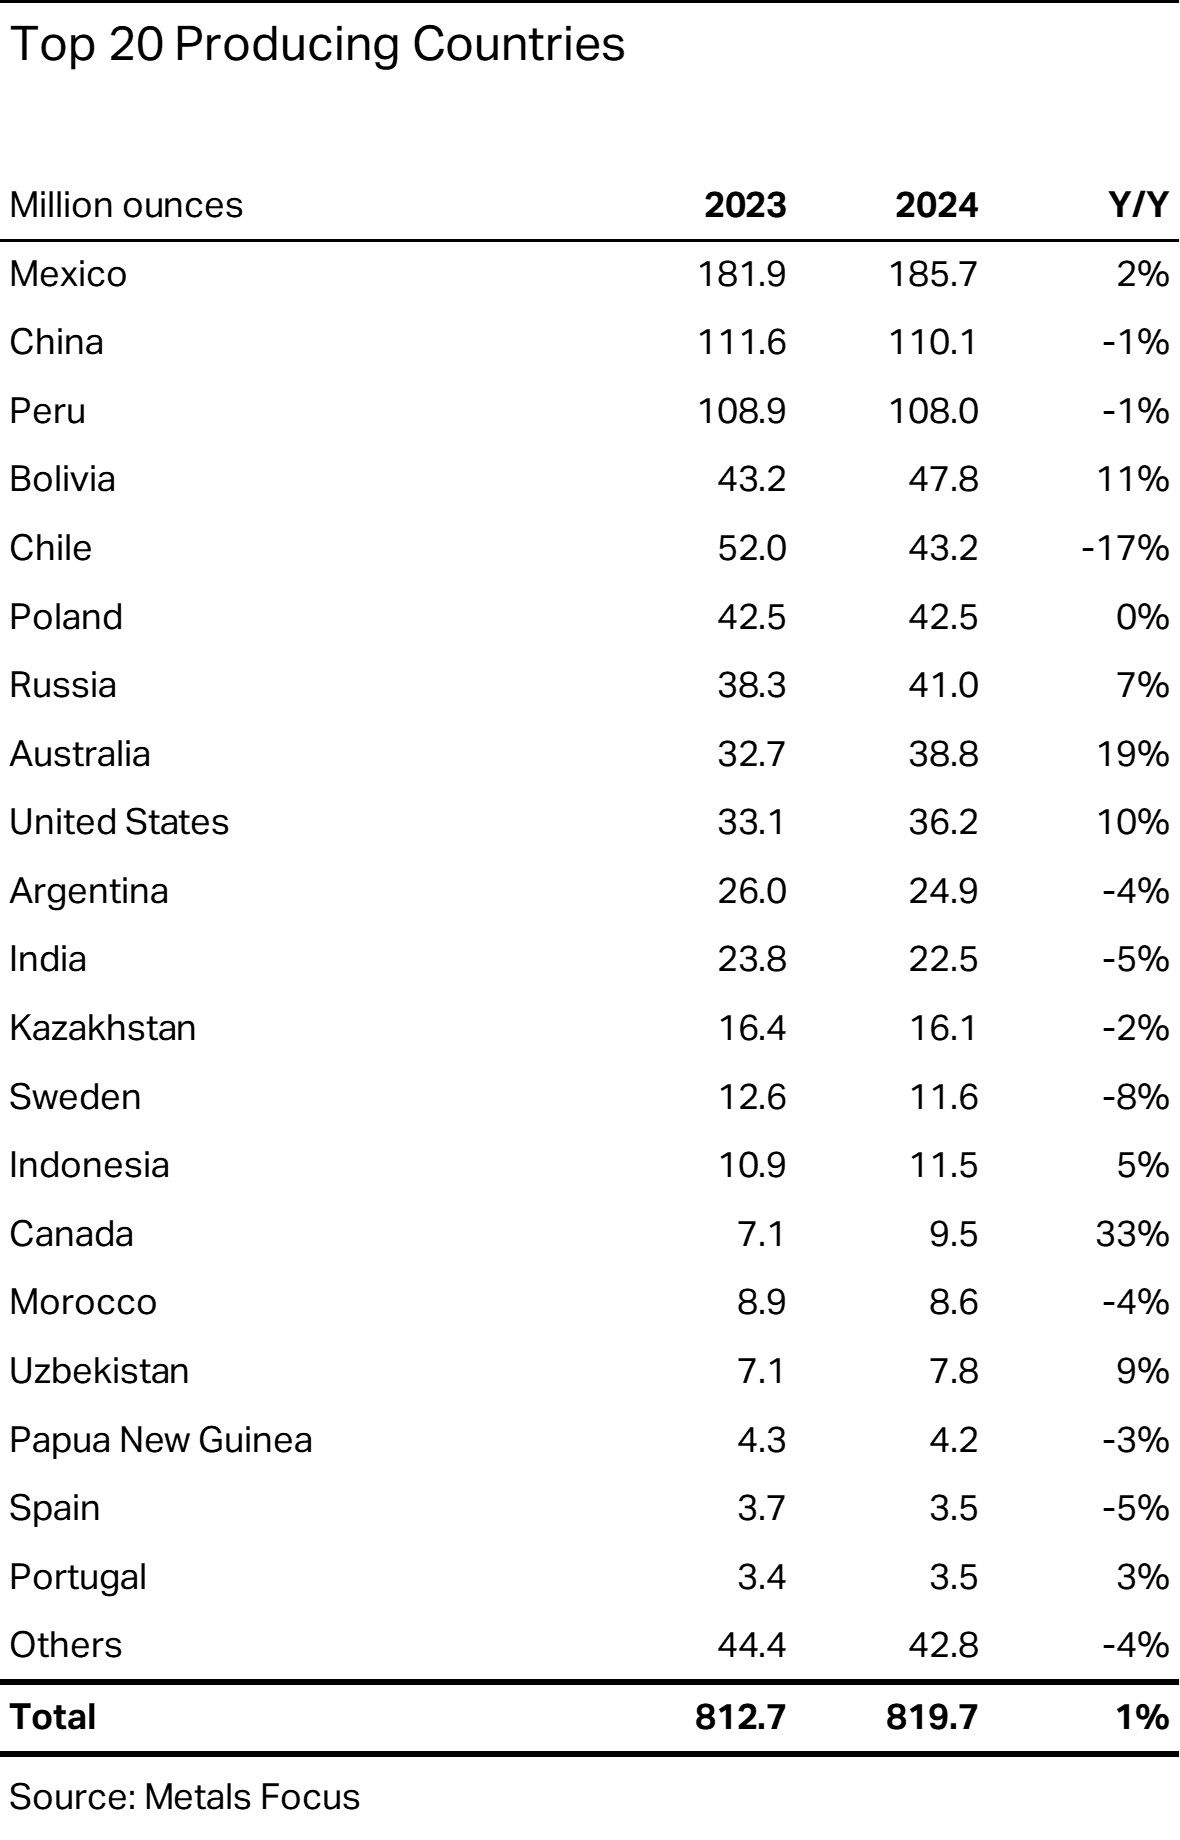
Global silver mine production rose 0.9 percent in 2024 to reach 819.7 million ounces, according to data compiled by the Silver Institute in partnership with Metals Focus. The increase came primarily from higher output at lead and zinc mines in Australia and a recovery in Mexican supply after Newmont's Penasquito mine returned to full production.
Additional growth came from Bolivia and the United States, helping offset an 8.8 million ounce decline in Chilean output. Silver production tied to gold mining also posted the strongest gain of any source category, up 12 percent year over year to a three year high of 13.9 million ounces.
Mexico remained the largest silver mine producing country in 2024, followed by China, Peru, Bolivia and Chile, with the United States ranking among the top producing nations tracked in the Silver Institute's annual survey. US mines, including Hecla Mining's Greens Creek and Lucky Friday operations and Coeur Mining's Rochester mine in Nevada, contributed to the domestic total even as lead and zinc byproduct mining remained the dominant global source of supply.
On the demand side, industrial applications continue to anchor the market. Electronics, solar panels and medical devices all draw on silver's conductive and antimicrobial properties, and record electronics and electrical demand has been driven in part by growth in artificial intelligence infrastructure, much of it built and operated in the United States.
The Silver Institute's data underscores a market where mine supply growth has struggled to keep pace with expanding industrial and investment demand, a gap that has persisted for multiple consecutive years.
Source: Silver Institute - https://silverinstitute.org/silver-supply-demand/