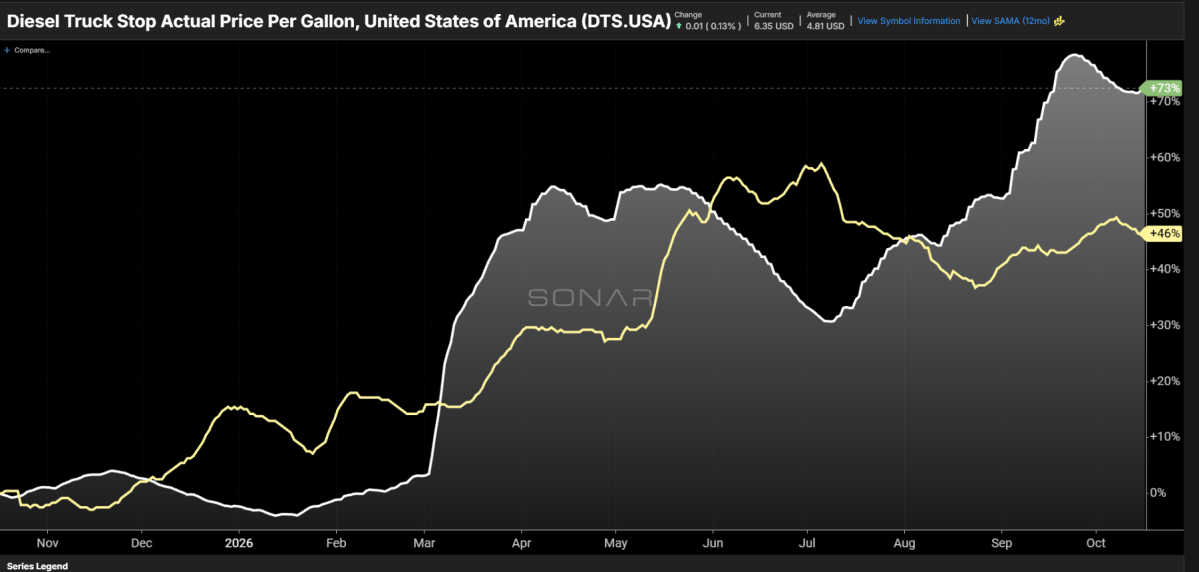
Retail diesel prices are up 73% from a year ago, while dry van spot rates have risen 43%, according to the FreightWaves Chart of the Week built on SONAR data.
The chart plots the SONAR Diesel Truck Stop Actual Price per Gallon for the United States against its year-over-year change since late October 2025. The series stood at $6.35 per gallon, compared with a 12-month average of $4.81. The year-over-year line climbed sharply from March, eased through the summer, then rose again to a peak above 70% in late September and has held near 73% since.
FreightWaves market analysis notes that spot rates have not kept pace with fuel over the past few months. That gap squeezes carrier profitability and makes cash flow harder for smaller carriers to manage. The analysis contrasts the current cycle with the early COVID period, when diesel prices fell in 2020 and fuel costs were not part of the margin pressure.
Capacity indicators point the same direction. The Accepted SONAR Truckload Volume Index fell more than 4% over four weeks to 9,518, its lowest level outside a holiday week since January. The national tender rejection rate holds near 13.9%, compared with under 6% a year earlier, when accepted volumes were roughly 2% higher.
The analysis traces the current rate cycle to the 2025 holiday season, when rejection rates and spot rates ran above the prior three years, with Winter Storm Fern in late January adding pressure. Higher borrowing costs have made carriers that survived the downturn from mid-2022 to late last year hesitant to add trucks.
FreightWaves advises that transportation procurement teams should expect a market that stays tighter into 2027.
Source: FreightWaves - https://www.freightwaves.com/news/no-signs-of-truckload-capacity-recovering